

When “Okay Lang Ako” Doesn't Tell the Whole Story
“Okay lang ako.”
For many Filipino-Americans, those three words can mean more than they appear to.
They can mean, “I'm trying to manage.”
They can mean, “I don't want anyone to worry.”
Or sometimes, “I'm struggling, but I'm not ready to talk about it.”
When it comes to money, this can be especially difficult.
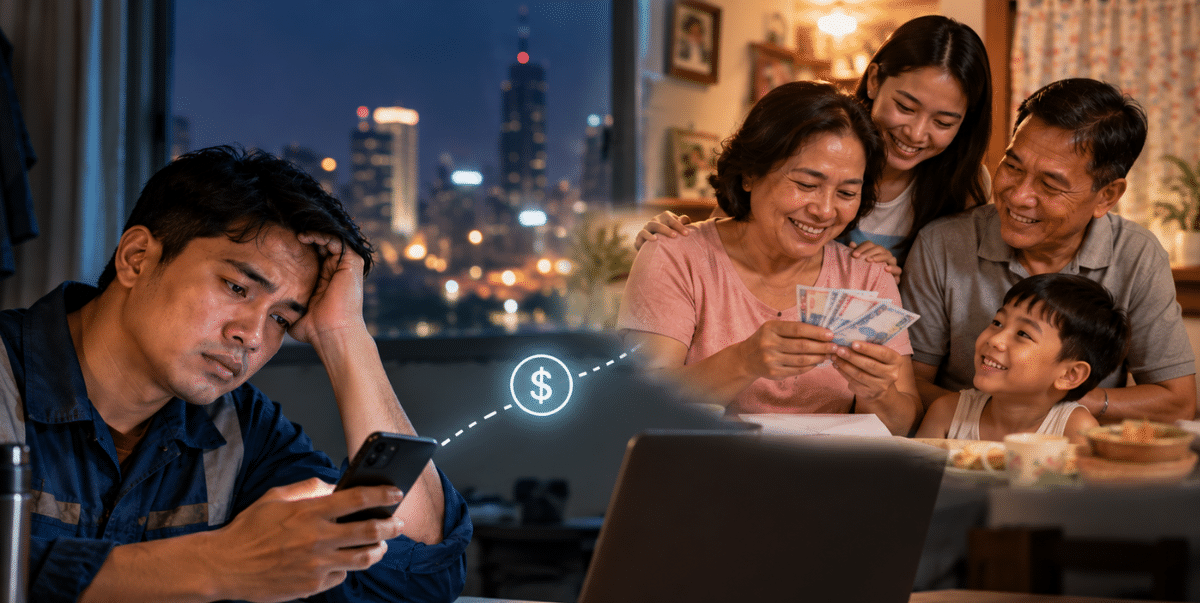
Debt isn't always visible. You can go to work, attend family gatherings, send money home, help relatives, and appear completely fine while quietly worrying about credit card balances and monthly payments.
And for some Filipino-Americans, the cultural value of hiya—a sense of shame, embarrassment, or concern about how one's actions affect their dignity and relationships—can make talking about financial problems even harder.
But struggling with debt isn't a character flaw.
And asking for help isn't failure.
Sometimes, the most responsible thing you can do for yourself and your family is to stop hiding the problem and start understanding your options.
What Is “Hiya,” and How Can It Affect Financial Decisions?
Hiya is deeply connected to Filipino ideas about dignity, respect, propriety, and social relationships.
In everyday life, it can encourage us to think about how our actions affect others.
That's not necessarily a bad thing.
The challenge comes when the desire to avoid embarrassment becomes so strong that we avoid addressing a serious problem.
Debt can become one of those problems.
You might think:
- “Ayokong malaman ng family ko.”
- “Baka isipin nila irresponsible ako.”
- “I should be able to handle this myself.”
- “Nakakahiya humingi ng tulong.”
- “What will people say?”
- “Maybe I can fix it next month.”
So you keep going.
You make the minimum payment.
You use another card.
You transfer a balance.
You borrow money.
You tell yourself you'll catch up after the next paycheck.
Meanwhile, the underlying problem remains.
The “Saving Face” Trap Can Make Debt More Expensive
Trying to maintain appearances can have a financial cost.
Imagine someone has $20,000 in credit card debt spread across several accounts.
They've been making minimum payments but aren't making much progress because of interest and other expenses.
Then a family emergency happens.
Instead of telling their family that they're already struggling financially, they use another credit card to help.
The intention is loving.
But now the person has even more debt.
This is one of the difficult realities of financial stress:
Trying to hide a financial problem can sometimes make the problem larger.
Protecting your dignity shouldn't require sacrificing your financial future.
Debt Does Not Define Your Worth
One of the most important things to understand is that debt is a financial condition—not an identity.
Having credit card debt doesn't mean you're lazy.
It doesn't mean you're irresponsible.
It doesn't mean you've failed your family.
People accumulate debt for many different reasons:
- Unexpected medical expenses
- Job loss or reduced income
- Supporting family
- Emergency travel
- Rising household costs
- Major home or car repairs
- Divorce or separation
- Business difficulties
- Accumulated credit card spending
- Simply trying to make ends meet during a difficult period
Sometimes, several of these things happen at once.
What matters is what you do after you recognize the problem.
The First Step Isn't Fixing Your Debt—It's Facing It
You don't have to solve everything in one day.
Start by knowing what you're dealing with.
Gather your credit card and loan statements and write down:
Your Total Balances
How much do you owe across all accounts?
Don't rely on memory.
Your Interest Rates
Which accounts are charging the highest interest?
Your Minimum Payments
How much are you required to pay every month?
Your Monthly Income
How much money actually comes into your household?
Your Essential Expenses
How much do you need for housing, food, utilities, transportation, healthcare, insurance, and other necessities?
Once you see the complete picture, you can begin making decisions based on facts rather than fear.
You Don't Have to Tell Everyone
Overcoming hiya doesn't mean announcing your financial situation to your entire family.
You get to decide who you trust.
You may start with:
- Your spouse or partner
- A trusted family member
- A qualified financial professional
- A nonprofit financial counselor
- Another professional who can help you understand your options
The goal isn't to make your private finances public.
It's to make sure you aren't carrying the entire burden alone.
Sometimes one honest conversation can be the beginning of a much better financial plan.
Debt Consolidation vs. Debt Settlement: Understand the Difference
If you're researching debt help, you'll likely encounter terms such as debt consolidation and debt settlement.
They are not the same thing.
What Is Debt Consolidation?
Debt consolidation generally involves combining multiple debts into one payment, often through a new loan or financial product.
The potential advantage is simplicity: instead of managing several payments, you may have one.
However, consolidation doesn't automatically make debt disappear.
Depending on the terms, interest rate, fees, and repayment period, you could still pay a significant amount over time.
It's important to compare the full cost before moving forward.
What Is Debt Settlement?
Debt settlement is a different approach.
Generally, it involves negotiating with creditors to resolve eligible unsecured debts for less than the amount owed.
However, debt settlement isn't right for everyone.
There can be potential consequences, including impacts on credit, collection activity, fees, and possible tax implications.
Creditors are also not required to accept settlement offers.
That's why anyone considering debt settlement should understand the process, risks, alternatives, and potential costs before enrolling.
Asking for Help Is Not the Same as Giving Up
There is a misconception that strong people solve everything themselves.
But financial strength isn't necessarily about handling every problem alone.
Sometimes it's about recognizing when your current strategy isn't working.
If you're making minimum payments every month but your balances barely move, continuing to do exactly the same thing may not improve your situation.
Getting professional guidance doesn't mean someone else is taking control of your finances.
It means you're gathering information so you can make a more informed decision.
That's strength.
A New Way to Think About “Hiya”
Instead of thinking:
“Nakakahiya na may utang ako.”
Try thinking:
“Mas nakakahiya kung alam kong may problema pero wala akong ginagawa.”
Debt doesn't become less real because nobody knows about it.
And asking for help doesn't make the debt more embarrassing.
It can be the first step toward changing it.
Your family's long-term financial security is more important than maintaining the appearance that everything is perfect today.
Protecting Your Family's Future May Require an Uncomfortable Conversation
For Filipino-Americans supporting parents, children, siblings, or relatives, debt can become especially complicated.
You may feel responsible for keeping everyone else financially secure.
But if your own finances collapse, you may eventually become unable to help anyone—including yourself.
That's why responsible debt management isn't selfish.
It's part of protecting your family's future.
Think about it this way:
Short-term embarrassment vs. long-term financial stability.
Which one would you rather choose?
A difficult conversation today could prevent years of financial stress.
What to Do If You're Afraid to Ask for Help
If hiya is keeping you from addressing your debt, start small.
Step 1: Write Down the Numbers
You don't have to tell anyone yet.
Just understand your own situation.
Step 2: Stop Adding Unnecessary Debt
If possible, avoid using credit cards to fund non-essential expenses while you're working on your financial situation.
Step 3: Protect Your Essentials
Prioritize housing, food, utilities, healthcare, transportation, and other necessary expenses.
Step 4: Build a Small Financial Cushion
Even a starter emergency fund can help prevent every unexpected expense from becoming another credit card balance.
Step 5: Learn Your Options
Research debt repayment, consolidation, credit counseling, debt settlement, and other potential strategies.
Step 6: Talk to a Professional
You don't have to commit to a solution simply because you ask questions.
A consultation can be an opportunity to understand what may—or may not—fit your circumstances.
A Simple Mindset Shift: From “Saving Face” to “Saving Your Future”
Imagine two people facing $25,000 in credit card debt.
Person A hides it.
They continue making minimum payments, avoid discussing the problem, and use their available credit when emergencies happen.
Person B acknowledges the situation.
They review their budget, understand their debt, seek professional guidance, and explore their available options.
Neither person should feel ashamed of having debt.
But only one has actively started addressing the problem.
The difference isn't perfection.
It's action.
You Can Be Proud of Your Family and Still Set Financial Boundaries
For many Filipino-Americans, family responsibilities are part of what motivates them to work hard in the first place.
You want to provide.
You want to help.
You want your parents to be comfortable.
You want your children to have opportunities.
Those values don't have to disappear when you're dealing with debt.
But sometimes, helping your family means making difficult financial decisions today so you can remain financially capable tomorrow.
That might mean saying:
“I can't afford to send that amount right now.”
Or:
“I need to take care of my debt first.”
Or:
“Let me see what I can realistically contribute.”
Those aren't statements of failure.
They're statements of responsibility.
You Don't Have to Be Ashamed of Asking for Help
Hiya can encourage us to protect our dignity and the people we care about.
But your financial future deserves protection, too.
If you're struggling with debt, you don't have to wait until the situation becomes unbearable before doing something about it.
Start with the numbers.
Understand your options.
Ask questions.
And have the courage to take the first step—even if that first step is simply admitting:
“I need help understanding my debt.”
That's not failure.
That's where progress can begin.
Ready to Take the First Step?
If you're carrying credit card or other qualifying unsecured debt and aren't sure what to do next, Financial Rescue can help you understand your situation and explore potential options.
Our debt consultants can provide a free, no-obligation consultation so you can ask questions and learn more before making any decisions.
You don't have to hide behind “okay lang ako.”
And you don't have to figure everything out alone.
Contact Financial Rescue today for a free consultation and take a brave, informed step toward a stronger financial future.